

Real Client Scenarios: Credit Repair Wins From Bakersfield
Five real situations from Bakersfield clients we’ve worked with since 2016. Names changed for privacy. The strategy is real.
Numbers on a credit report aren’t just numbers — they’re whether you can buy a house, drive a reliable car, or sleep through the night without worrying about a collector calling. Here are five real situations from Bakersfield clients we’ve worked with since 2016. Your story might look a lot like one of these.
The First-Time Homebuyer in Northwest Bakersfield
- Disputed both medical collections under FCRA §611 with debt validation letters under FDCPA §809
- Both collectors failed to validate within 30 days → both deleted
- Sent a goodwill letter to the auto lender citing two years of perfect payments since the late
- Auto late removed as a goodwill courtesy
Mid-FICO improved enough to meet the lender’s requirements. Closed on a 3-bedroom in Northwest Bakersfield three months later.
The Single Mom Recovering From Identity Theft
- Filed identity theft affidavit with the FTC at IdentityTheft.gov
- Used the affidavit to file FCRA §605B blocked-reporting demands with all three bureaus
- Filed a police report with Bakersfield PD
- Frozen credit at all three bureaus
All five fraudulent items removed. The score improved once the legitimate accounts were the only thing showing.
The Construction Worker With Old Charge-Offs
- Pulled Metro 2 data and identified Date of First Delinquency errors on both charge-offs (re-aged)
- Submitted FCRA §623 disputes directly with the furnishers, citing Metro 2 non-compliance
- Negotiated pay-for-delete on the open collection — paid 40% in exchange for written deletion agreement
Both charge-offs deleted (re-aging violation). Open collection deleted after PFD. The score improved.
The Couple With High Credit Card Utilization
- Built an AZEO payoff plan over 60 days
- Coordinated payment timing to statement closing dates
- Requested credit limit increases on three seasoned cards (no hard pulls)
Both scores improved. No disputes filed — pure utilization strategy.
The Senior on Fixed Income Facing a Garnishment
- Reviewed the underlying debt — collector could not produce chain of title
- Helped client prepare a pro se Notice of Opposition to Claim of Exemption in Kern County Superior Court
- Sent FDCPA §809 validation demand to the debt buyer
- Filed FCRA dispute citing the unverified judgment
Garnishment opposition led to settlement at 25% of original demand. Judgment vacated by stipulation. Tradeline deleted. The score improved.
When Lawsuits Get Dismissed
Some clients come to us already being sued by creditors or third-party debt buyers. Here are two recent cases where the lawsuits were dismissed within months of the client engaging our consumer-protection support services.
⚖️ Important Legal Notice — Please Read
Maximum Score Builders is not a law firm and does not provide legal advice or legal representation. The dismissals shown below were the outcome of legal proceedings, not the result of credit repair services alone.
Our role with these clients was to provide consumer-protection support — including FDCPA §809 debt validation demands, document organization, and education about FCRA, FDCPA, and Rosenthal Act consumer rights. Clients made their own legal decisions and, where appropriate, were referred to or worked with licensed California attorneys.
If you are facing a lawsuit, judgment, or wage garnishment, you should consult with a licensed California attorney. The State Bar of California Lawyer Referral Service can be reached at calbar.ca.gov.
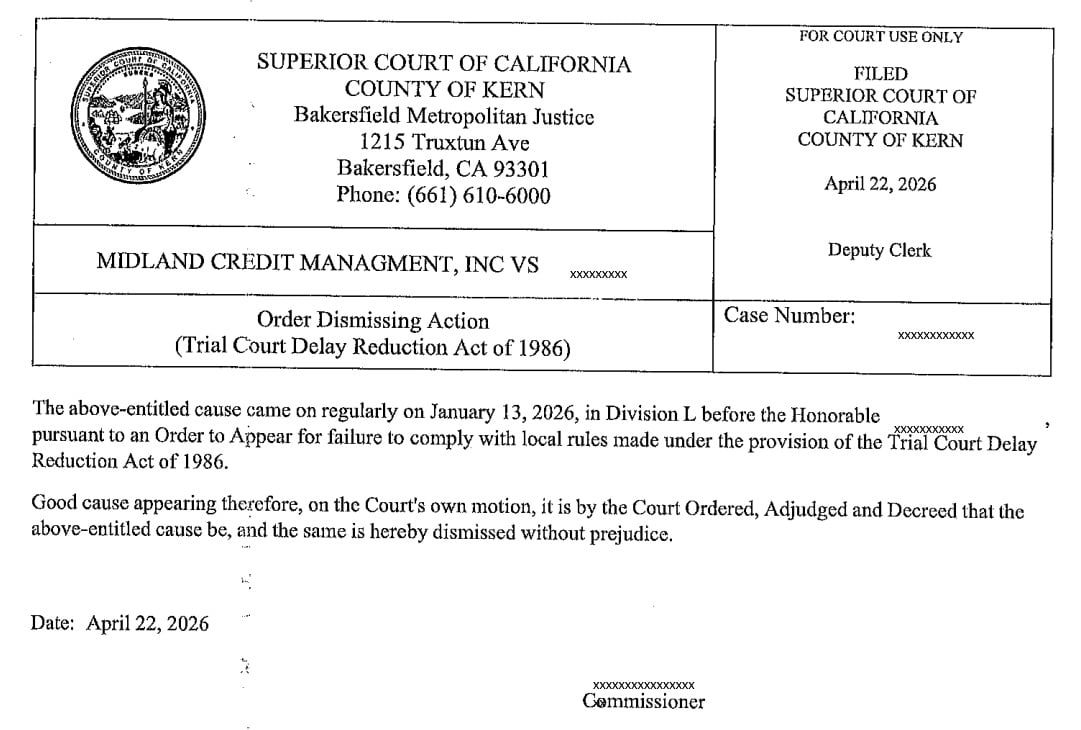
Creditor Lawsuit Dismissed
This client came to us after being served with a debt collection lawsuit from a third-party debt buyer. Through documented FDCPA §809 validation demands, the underlying debt could not be verified. The client worked with a California-licensed attorney for the court process, and the case was dismissed.
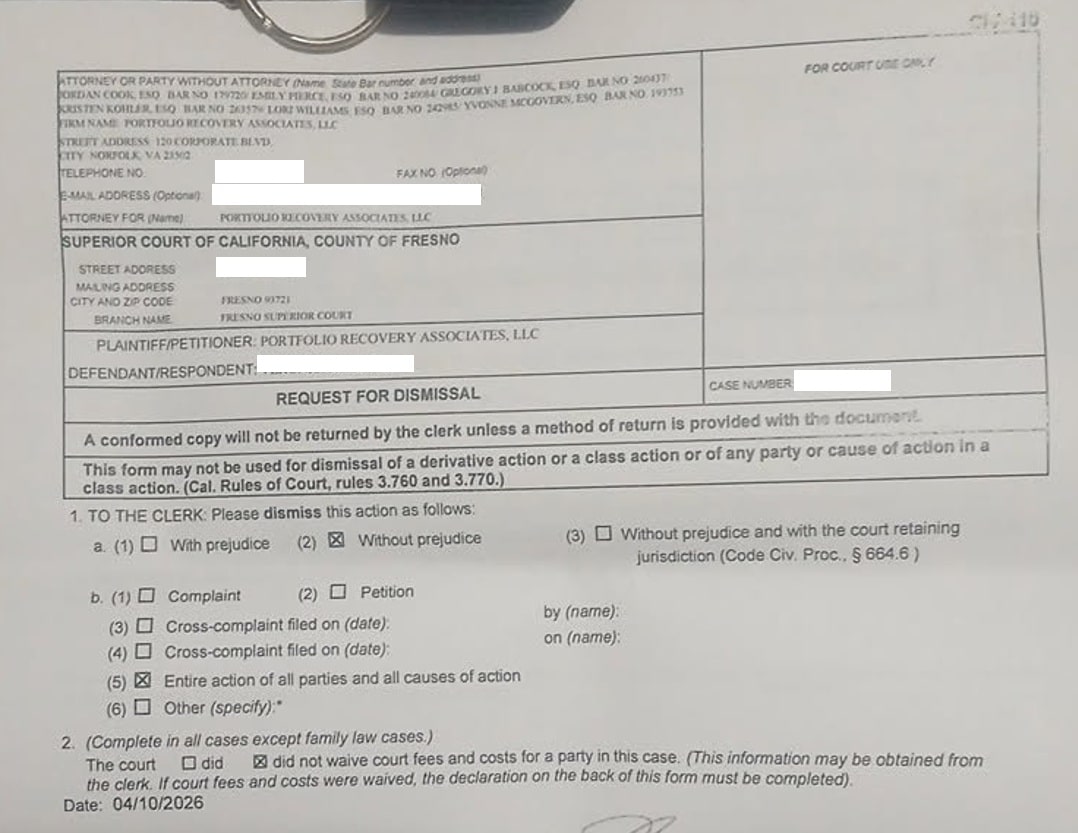
Debt Collector Case Dismissed
Another Bakersfield client served with a collection lawsuit from a junk-debt buyer. After validation demands and a coordinated legal response, the case was dismissed. The associated negative tradelines were also disputed under FCRA §611 and removed from the credit report.
Some clients leave reviews after their lawsuits are dismissed. Some after they hit their target score. Some just because the process felt different than what they expected. Here are their words.
What Bakersfield Says About Us
Very helpful people and they listen to your concerns. Thanks to Isaac and staff.
Excellent customer service. Quick to respond and always available for guidance.
I had a couple of collections affecting my credit score so I went to Isaac for some guidance on getting things sorted out and he was very knowledgeable and passionate about his work. He helped me from start to finish and went beyond my expectations and I’m very grateful for what he and his team did for me. I would recommend him to anyone that’s in need of financial and credit guidance — it’s not easy doing it alone and good help isn’t easy to find nowadays. Thank you Isaac and the team at Maximum Score Builders!
Isaac Palacios has done everything he has told me he could do regarding my account and after several months I’ve finally received 710+ score! Never thought it was possible with the accounts and history I’ve made at such a young age!
What These Stories Have in Common
Every one of these wins came from the same playbook:
- Pull all three reports — never work from one bureau
- Identify the actual violation — Metro 2, FCRA, FDCPA, or all three
- Cite the exact law in every dispute letter
- Track every deadline — bureaus are bound by 30-day timers
- Combine strategies — utilization fixes plus disputes plus goodwill
There’s no magic. There’s just law, leverage, and patience.
Frequently Asked Questions
Are these results typical?
Results vary based on the items on your report, the responsiveness of furnishers, and your own credit habits. We make no guarantees about results — that would violate CROA. We do maintain a written 90-day refund policy, subject to the eligibility conditions stated in that policy and your service agreement.
How long does most credit repair take?
Timing depends on the items on your report and how quickly bureaus and furnishers respond. Bureaus generally must investigate a dispute within 30 days (up to 45 in some cases), and many files take several rounds. No specific result or timeline is guaranteed.
Do you work with people who have bankruptcies?
Yes. Discharged bankruptcies stay on your report for 7 (Chapter 13) to 10 (Chapter 7) years, but the individual accounts included in the bankruptcy must be reported correctly. Errors on those tradelines are very common and disputable.
Can you really remove old collections?
Sometimes — when they’re inaccurate, unverifiable, or non-Metro-2-compliant. We never promise a specific deletion. We promise to fight for it within the law.
Your Story Could Be Next
If any of these scenarios sound like you, get a free assessment. We’ll pull your reports, find the violations, and tell you honestly what we can and can’t do.
Get Your Free Assessment Call (661) 505-8085These real-world credit repair scenarios demonstrate that meaningful score improvements are achievable with the right strategy. First, understanding which negative items are disputable under the FCRA is essential. Furthermore, each situation requires a tailored approach — for example, a client with a repossession needs a different strategy than one with medical collections. Additionally, working with a No Advance Fees firm like Maximum Score Builders ensures that all dispute work is done in a FCRA-focused manner. As a result, clients avoid common pitfalls and see faster, more reliable results.
However, there is no universal timeline: every credit profile is different, and some files require several months of consistent effort. In contrast to DIY credit repair, professional guidance helps clients prioritize the items most likely to yield score gains. Overall, these case studies show that with patience and the right expertise, substantial credit improvement is within reach for most consumers. If you see yourself in any of these scenarios, consider scheduling a free credit analysis with our Bakersfield team.
Client experiences vary. The work focuses on the accuracy and completeness of the information being reported: identifying items that appear inaccurate or unverifiable, disputing them with the credit bureaus and furnishers, and coaching on credit-management habits such as utilization. What changes on any individual report depends on the responses from the credit bureaus and furnishers and on each consumer’s individual credit profile, and no specific score increase can be predicted. Credit decisions for mortgages, auto financing, and rental housing are made independently by lenders, dealers, landlords, or other providers under their own criteria.
Timelines vary from client to client. If a dispute results in a deletion or correction, that change may appear after the bureau or furnisher completes the applicable investigation and updates the reported information. More complex situations with multiple collections or serious derogatory items may take longer to address, and outcomes vary based on the information being reported and the consumer’s circumstances.
Maximum Score Builders serves Bakersfield and Kern County clients dealing with collections, late payments, charge-offs, identity theft errors, medical debt, student loan issues, and more. Many clients are preparing to buy a home, start a business, or improve their overall financial position.
Yes. Many mortgage denials are due to specific credit score or credit report issues that can be addressed. Credit repair does not guarantee eligibility or approval for an FHA, conventional, or other mortgage. Mortgage eligibility depends on the lender and loan program, including applicable credit, income, debt, property, and other underwriting requirements. Coordinating with a local lender and credit repair specialist together maximizes results.
Yes, but it takes time. FHA requires a minimum 3-year waiting period after foreclosure (less with extenuating circumstances). During that time, rebuilding credit through secured cards, on-time payments, and reducing debt sets the stage for qualification. With diligent effort, reaching the required 580–620 minimum is achievable.
This article is for general education only and is not legal or financial advice. Results vary, and no specific outcome is guaranteed. See our editorial policy.